The financial services industry has changed considerably as consumers seek faster, more convenient ways to access credit. Banks remain important lenders, but specialist finance companies also offer personal loans, debt consolidation, and property-related borrowing. One name that appears in online searches is qlcredit, commonly associated with QL Credit Gain Finance Company Limited in Hong Kong.
Unlike the descriptions found on some websites, qlcredit is not a verified private individual, celebrity, or universally recognized consumer credit score. Its clearest documented identity is connected to a financial lending business operating within the Credit Gain group.
Public corporate disclosures, company materials, and Hong Kong’s regulatory framework provide useful evidence about the business and its activities.
This article examines qlcredit’s background, corporate relationships, financial products, lending procedures, privacy practices, and consumer protections. It also explains why checking official records matters before entering any borrowing agreement.
What Is qlcredit?
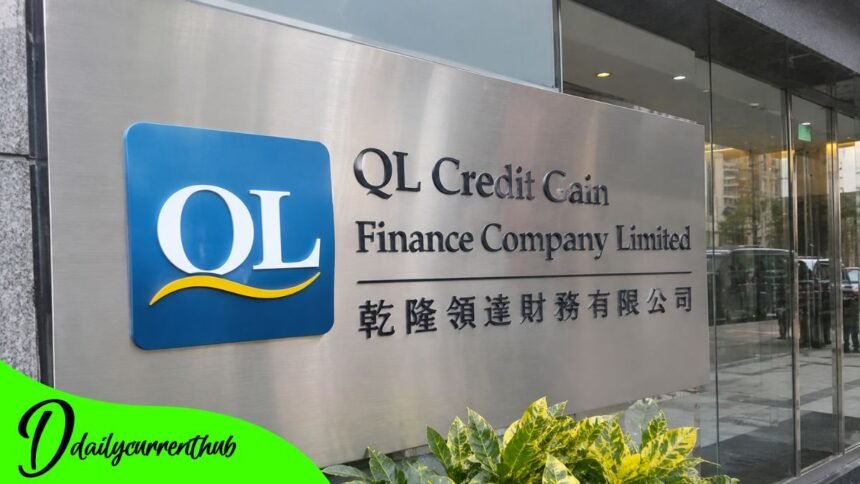
qlcredit is a search term linked to QL Credit Gain Finance Company Limited, a Hong Kong-based finance company involved in money lending.
The company’s identity is supported by a June 11, 2026 announcement issued by China Financial Services Holdings Limited through the Hong Kong Stock Exchange. That document identifies QL Credit Gain Finance Company Limited as an indirect wholly owned subsidiary operating with a money lender’s license under Hong Kong’s Money Lenders Ordinance.
The company is associated with Credit Gain, which presents several financing solutions for consumers and property owners.
Its business differs from a traditional bank because a licensed money lender is not automatically authorized to provide the full range of banking services, including ordinary deposit-taking accounts.
For consumers researching qlcredit, the most valuable information concerns the company’s legal identity, products, financial obligations, and applicable regulation.
Understanding these distinctions helps prevent confusion with similarly named lenders or unrelated online credit services.
The Background and Development of qlcredit
Early History and Corporate Identity
The Credit Gain business describes a presence in Hong Kong spanning nearly two decades. Its corporate information identifies QL Credit Gain Finance Company Limited and KP Credit Gain Finance Company Limited as companies belonging to the same listed financial group.
These legal identities matter because customers may encounter the shared Credit Gain branding without immediately recognizing the separate companies involved.
Hong Kong corporate and financial disclosures provide a more reliable account of the business than unsupported claims about its founders or technological innovations.
For example, the June 2026 stock exchange announcement establishes that QL Credit Gain Finance Company Limited participated in a mortgage lending transaction.
The announcement does not establish the company’s original founding date, founder’s identity, or every stage of its history. Those details should not be inferred simply from the wider group’s years of operation.
The documented background places QL Credit within Hong Kong’s non-bank finance sector rather than an unidentified international lending platform.
Corporate Ownership and Partnership
QL Credit Gain Finance Company Limited has a documented corporate relationship with China Financial Services Holdings Limited.
The parent company is listed on the Hong Kong Stock Exchange under stock code 605, while QL Credit Gain was identified as an indirect wholly owned subsidiary in June 2026.
This relationship is relevant because financial companies within listed groups may appear in corporate announcements when transactions meet applicable disclosure requirements.
One example occurred on June 11, 2026, when QL Credit Gain agreed to a HK$23 million mortgage loan with a one-year term.
The published transaction demonstrates activity in property-backed lending beyond the company’s advertised consumer loan products.
However, belonging to a listed group does not guarantee that every loan is inexpensive, suitable, or approved. Individual borrowers still need to evaluate the specific company, contract, and lending conditions.
qlcredit Loan Products and Financial Services
Personal Loans and Borrowing Options
The Credit Gain website advertises personal lending for customers needing financial assistance or access to additional funds.
Its personal loan promotional materials describe several features:
- Advertised annual interest rates starting from 10%.
- Repayment periods between 6 and 60 months.
- A maximum advertised loan amount of HK$2 million or 25 times monthly salary, whichever is lower.
- The possibility of receiving approved funds within 24 hours.
These are advertised terms, not guaranteed offers. Actual borrowing limits, interest rates, approval decisions, and processing times depend on the lender’s assessment.
A potential borrower should obtain a written explanation of the complete repayment obligation before accepting an offer.
A low starting interest rate can attract attention, but it does not necessarily apply to every applicant.
Debt Consolidation and Property Financing
Credit Gain also advertises debt consolidation, property-owner loans, and mortgage financing.
Debt consolidation generally involves combining existing debts into a new repayment arrangement. Depending on the contract, this can simplify payments, although extending the repayment period may increase total borrowing costs.
Property-owner lending is another advertised category. The company describes options for eligible property owners, including certain circumstances where an existing mortgage is already present.
Its property-owner loan materials advertise financing up to HK$2 million and repayment terms of up to 120 months.
Property-related products require careful evaluation because a loan’s legal structure, any security involved, and the consequences of missed payments can differ significantly.
Consumers should establish whether a facility is secured or unsecured, what rights the lender receives, and whether additional legal obligations apply.
How qlcredit Works Behind the Scenes
Application Assessment and Credit Evaluation
The company’s published customer declaration and privacy documentation explain several aspects of its application process.
Applicants may be required to supply personal information, identity details, financial information, and other documents needed for assessing creditworthiness.
The company also states that it may obtain information from credit reference agencies when considering an application.
Its privacy policy discusses credit assessments, periodic reviews, and creating or maintaining internal credit-scoring models.
This is different from providing a publicly accessible consumer credit score.
Financial institutions use credit-related information to evaluate lending risks, but the existence of an internal scoring model does not prove that an official product called the “qlcredit score” exists.
Customers should understand which information is required, how it will be assessed, and whether their application involves a credit reference inquiry.
Interest Rates and Repayment Responsibilities
The total cost of a loan deserves as much attention as the amount borrowed.
Credit Gain’s website provides a representative repayment illustration involving HK$10,000 borrowed at an annual interest rate of 30%, with 12 installments of HK$975 and a total repayment of HK$11,700.
This illustrates how borrowing costs increase the total amount repaid.
In Hong Kong, the Money Lenders Ordinance generally prohibits effective annual interest rates exceeding 48%. A rate above 36% may also trigger a legal presumption that the transaction is extortionate, subject to applicable legal provisions.
These statutory thresholds are not recommendations for acceptable borrowing costs.
Borrowers should compare effective annual rates, total interest, fees, repayment periods, and any contractual consequences of default.
An affordable monthly installment should be assessed alongside the full cost over the loan’s lifetime.
Customer Privacy and Data Protection
Handling Sensitive Financial Information
Customer privacy is central to any financial lender.
QL Credit Gain Finance Company Limited publishes a privacy policy and a personal information collection statement explaining how it may collect, use, retain, and disclose customer information.
The stated purposes include processing financial applications, assessing credit, maintaining financial relationships, managing outstanding debts, and meeting regulatory obligations.
Its documents also describe circumstances in which information may be shared with service providers, other financial institutions, and credit reference agencies.
The customer declaration discusses potential cross-border transfers of personal data, including to parties in jurisdictions where privacy protections may differ from those in Hong Kong.
Consumers should read these conditions before submitting identification documents or financial records.
A published privacy policy demonstrates that information-handling practices are described, but it does not independently guarantee that a company’s security systems are free from risk.
Regulatory Status and Consumer Protection
Licensing Under Hong Kong Law
Money lending in Hong Kong is regulated under the Money Lenders Ordinance, Chapter 163.
The Companies Registry maintains publicly accessible resources to check licensed money lenders, while the Licensing Court grants licenses.
The Credit Gain website displays money lender license reference 1988/2025 for QL Credit Gain Finance Company Limited.
A June 2026 Hong Kong Stock Exchange announcement also identifies the company as holding a money lender’s license at that time.
However, those records do not by themselves verify that the license remains current on November 13, 2026. Borrowers should check the latest Companies Registry information for renewal or expiry details.
Hong Kong introduced additional lending safeguards effective August 1, 2026, including restrictions on requesting loan referees and debt-servicing-ratio limits for certain low-income unsecured personal loan applicants.
These measures illustrate the importance of responsible lending and repayment affordability.
How Customers Can Protect Themselves
Anyone considering a loan associated with qlcredit should verify the exact legal entity before providing sensitive information.
The company’s published contact details and registered information can assist with identity checks, but independent confirmation through official regulatory resources remains essential.
Customers should obtain the complete loan agreement, confirm all repayment terms, and ask questions about unclear charges.
They should also watch for impersonation attempts, unfamiliar intermediaries, requests for unexpected advance payments, and promises of unconditional loan approval.
A lender’s history or group affiliation should never replace a review of the actual agreement being offered.
Public Curiosity and Misconceptions About qlcredit
Is qlcredit a Credit Score or Digital Banking App?
Online explanations sometimes describe qlcredit as an artificial intelligence credit platform, a general financial technology framework, or a consumer credit score.
Such descriptions can confuse readers because they do not always identify a verifiable legal organization.
The strongest documentary connection is to QL Credit Gain Finance Company Limited and the wider Credit Gain lending business.
The company’s own materials refer to internal credit evaluation, but that is not the same as offering a standardized public credit score.
Likewise, insufficient official evidence describes qlcredit as a standalone worldwide banking application available to every consumer.
The distinction between a lender, credit bureau, credit score, and financial technology concept is fundamental to understanding what a particular service actually provides.
The Future of qlcredit
Technology, Regulation, and Responsible Lending
The Future of specialist lending in Hong Kong will be influenced by regulation, borrower protection, credit data practices, and changing customer expectations.
Digital application systems can make financial services more convenient, but greater convenience also creates responsibilities around personal data security and how borrowing costs are presented.
Hong Kong’s announced regulatory changes include a further phase scheduled for June 2027, involving credit information reporting requirements for money lenders engaged in unsecured personal lending.
For QL Credit Gain, the implications depend on its activities, compliance obligations, and future business decisions.
There is no basis for predicting a specific company expansion, new product launch, or financial performance without supporting announcements.
Its continuing relevance to borrowers will depend on the products offered, pricing, regulatory compliance, and the quality of information available to customers.
Conclusion
QL Credit is most clearly associated with QL Credit Gain Finance Company Limited, a Hong Kong lending business connected to China Financial Services Holdings Limited.
Official corporate disclosures establish the company’s participation in lending, while Credit Gain’s published materials describe personal loans, debt consolidation, property-owner financing, and mortgage-related services.
These facts provide a more dependable understanding of qlcredit than unverified claims about an international credit score or revolutionary artificial intelligence system.
For prospective borrowers, the most important questions concern current licensing, eligibility, effective interest rates, total repayment, contractual obligations, and personal information protection.
A financial company can offer convenient application procedures without necessarily providing the most suitable borrowing arrangement for every customer.
Understanding the lender’s legal identity and reviewing the actual terms remain essential steps in making an informed decision.
(FAQs)
1. What is qlcredit?
qlcredit is a term associated with QL Credit Gain Finance Company Limited, a Hong Kong-based non-bank money lending company.
2. Is qlcredit a bank?
No. QL Credit Gain Finance Company Limited is identified as a money lender rather than a conventional deposit-taking bank.
3. Who owns QL Credit?
A June 2026 corporate disclosure identifies QL Credit Gain Finance Company Limited as an indirect wholly owned subsidiary of China Financial Services Holdings Limited.
4. Does QL Credit provide personal loans?
The Credit Gain business advertises personal loans, debt consolidation, property-owner loans, and mortgage financing. Approval and conditions are subject to assessment.
5. What interest rate does qlcredit offer?
Credit Gain advertises personal loan annual interest rates starting from 10%. Individual offers may differ depending on the product and applicant.
6. Is qlcredit a legitimate financial company?
Its corporate identity and lending history are documented in company materials and Hong Kong Stock Exchange disclosures. Check current licensing directly with the Companies Registry.
7. Does qlcredit provide a consumer credit score?
No independently verified official product called a consumer-facing qlcredit score was identified. The company describes internal credit assessment practices.
8. What should customers check before applying to qlcredit?
Customers should verify the lender’s current license, confirm the legal company name, compare borrowing costs, review repayment obligations, and understand the privacy conditions.